UK Mortgages for Expats Living in Cyprus

We help British expats living in Cyprus secure a mortgage on a UK property. Contact us today to speak with our experienced expat broker team.

Bespoke Mortgage Advice for Expats Living in Cyprus

Dolphin Finance is an independent mortgage broker specialising in UK expat mortgages, including for British clients living in Cyprus. We advise on residential purchases, buy-to-let and refinancing UK property.

Cyprus has one of the largest British communities per head anywhere, built over decades through the military connection, the professional sector around Limassol and Nicosia, and a long-standing retirement population. Service and public sector pensions are particularly well regarded by lenders.

Whether you are serving, retired or working on the island, we can help. Contact us for a free initial consultation.
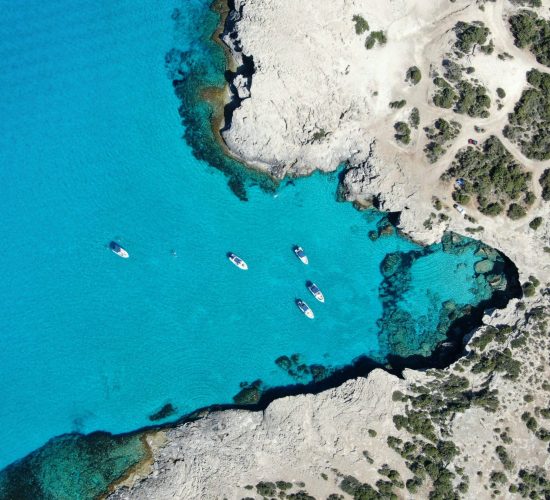
Cyprus, home to one of the largest British communities per head anywhere.

Why Expat Clients in Cyprus Choose Dolphin Finance

Specialist knowledge that the high street simply cannot offer.

We know which lenders to approach

Most expat application declines happen before they even reach an underwriter - automated systems flag overseas addresses and non-UK income. We match cases to lenders with manual underwriting who understand international clients, so your application goes to the right place first time. For applicants in Cyprus, that starts with knowing which lenders accept euro income - and on what terms.

We work around your time zone

Cyprus is two hours ahead of the UK, so we arrange calls, video and WhatsApp at times that work for you - and we keep you updated throughout the process without you chasing us.

Extensive lender panel

We are independent and not tied to any lender. We search the full specialist expat lender panel - private banks and offshore lenders included - and recommend the most suitable product for an expat mortgage from Cyprus, matched to your specific circumstances.

We handle the complexity

Overseas income documentation, foreign currency conversions, enhanced AML requirements, Power of Attorney for completion - we have dealt with all of it before and guide you through every step, so you are not navigating unfamiliar territory alone.
How It Works

A straightforward process, designed around your circumstances - and shaped for buyers arranging a UK mortgage from Cyprus.

1

Free initial consultation

We take the time to understand your full circumstances - where you're based, how you're paid, what you want to buy and your timescales. For expats living in Cyprus, that usually means assessing how a euro income alongside a UK, service or public sector pension is treated by UK lenders, so you get a clear picture before any formal process begins.

2

Lender selection & Agreement in Principle

We match your case to the right lenders from our specialist panel and secure an Agreement in Principle - essentially a conditional confirmation of how much they'll lend. It gives you the confidence to make an offer on a UK property while you're still overseas, and shows sellers your financing is credible.

3

Application & document support

We guide you through every document the lender needs - proof of your Cyprus address, overseas income evidence and source-of-funds paperwork, which tends to be scrutinised more closely on international cases. We then submit a complete, well-presented application to give you the best chance of approval first time.

4

Mortgage offer & completion

We manage the process through to formal mortgage offer, then co-ordinate with your solicitor towards completion - underwriting on expat cases can take a little longer, often four to eight weeks. Everything can be handled remotely, so there's no need to fly back to the UK.

Expat Mortgages in Cyprus - Your Questions Answered

Can I get a UK mortgage while living in Cyprus?+

Yes. Cyprus has one of the largest British communities per head anywhere, built over decades through the military connection, the professional services sector around Limassol and Nicosia, and a long-standing retirement population.

Most High Street banks will not lend to non-UK residents, so the workable deals sit with specialist lenders reached through a broker.

The ties between the two countries are close and the paperwork is familiar, which makes these among the more straightforward applications we handle.

I am serving with, or retired from, the armed forces in Cyprus. Does that change anything?+

It can help, and it is worth raising early. Serving personnel posted overseas are treated differently by several lenders from an ordinary expat applicant, and there are products aimed specifically at forces buyers.

Service and public sector pensions are also well regarded as retirement income, being predictable and index-linked, which matters if you are borrowing beyond your working life.

Tell us at the first conversation which of the two you are. The lender lists are different and starting on the right one saves a great deal of time.

Do UK lenders accept income paid in euros?+

Yes. The euro is one of the most widely accepted currencies in expat lending and the lender pool is wide.

Income in a foreign currency is still discounted in affordability calculations, commonly leaving 75% to 90% counted, as a standard buffer.

Anything paid in sterling, a UK pension, service pension or rental income, attracts no discount at all. Many Cyprus-based clients have some of each, so send the full picture rather than the largest single figure.

Why do British expats in Cyprus buy property in the UK?+

A base for family, a plan for returning, and investment. The community is unusually settled, so many of our Cyprus clients are not planning to move back at all and are buying an income-producing asset in a market they understand.

Others keep a property for children at UK universities or for visits home.

Each purpose is financed differently, so tell us which yours is at the start rather than after an application has gone in.

How big a deposit will I need, and can I get a buy-to-let mortgage?+

Residential lending reaches 90% loan-to-value, so deposits start from around 10% of the purchase price. Buy-to-let runs to 80%, so plan on at least 20%, and more where the rental figures are tight.

Buy-to-let is assessed mainly on the property's expected rent, which lenders typically want covering the payment by at least 125% and often 145% under their stress tests, alongside a minimum personal income.

Your solicitor's source-of-funds checks apply to every overseas buyer, so keep the trail complete.

Can I remortgage my UK property from Cyprus, and do I need to travel?+

Yes to the first and no to the second. Whether you are switching at the end of a rate or releasing equity from a property you already own, it is handled entirely from Cyprus.

Cyprus is two hours ahead of the UK, so calls sit inside both working days, and everything from the free initial consultation to completion runs remotely.

If your fixed rate ends within six months, start now.

Free initial consultation

Talk to an Expat Mortgage Specialist

Expert advice tailored to your circumstances - wherever in the world you live. No obligation.

Get a Free Quote